Direct Reduced Iron (DRI) Market
Direct Reduced Iron (DRI) Market (Grade: Grade – A (FeM – 81% Min), Grade – B (FeM – 78 To 80 %) and Grade – C (FeM – < 78%); Form: Pellets and Lumps; Production Process: Gas-based and Coal-based; and Region: North America, Europe, Asia Pacific, Latin America and Middle East & Africa)– Global Industry Analysis, Shares, Growth, Trends and Forecast 2021-2036
Categories:
All, Chemicals and Materials
| Format: PDF/PPT/Excel
| Product ID:
4948
| Report Version:
October 2026
- Report Preview
- Table of Content
- Request Customization
Market Snappshot
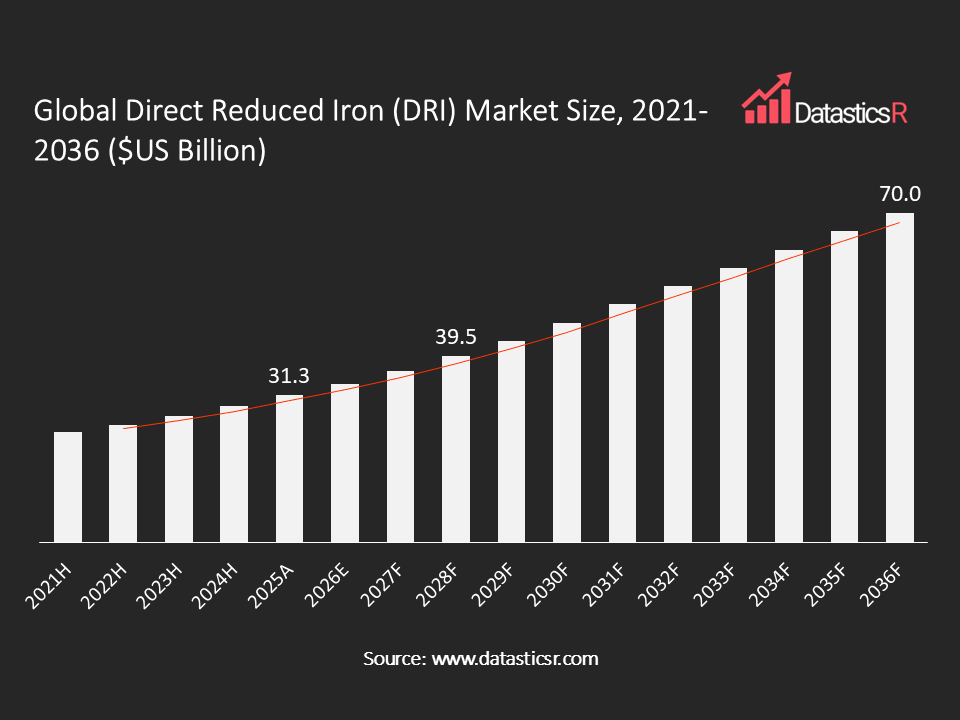
- Market Size in 2025: $US 31.3 Bn
- Forecast Market by 2036: $US 70 Bn
- CAGR for the Period 2026-2036: 7.6%
- Top Region in Terms of Market Share: Asia Pacific (48.8%)
- Key Players: Qatar Steel, JSW Ispat Special Products Limited, Kobe Steel Ltd, ArcelorMittal, NUCOR, Midrex Technologies Inc, Khouzestan Steel Company, Gallantt Group of Industries, Welspun Group, Jindal Shadeed Iron & Steel LLC and Others
Analyst Viewpoint:
The direct reduced iron (DRI) market is increasingly shaped by the convergence of steelmaking decarbonization, evolving furnace technologies, and the economics of securing high-quality metallic feedstocks. With steel producers, governments and customers looking to cut the emissions of steelmaking, new applications of DRI are emerging in electric arc furnace plants that need clean iron units, in integrated mills that use it to reduce blast furnace coke use, and in hot briquetted iron for shipment. Natural gas-based plants and coal-based plants share the market almost equally, and high-grade DRI with high iron content dominates because electric arc furnaces need low-residual feed. However, challenges remain in securing affordable natural gas and high-grade iron ore pellets, the cost and supply of green hydrogen, the metallization and carbon content that steelmakers require, and the lack of firm policy in some regions, which has already led some producers to delay hydrogen-based projects. At the same time, carbon pricing and border carbon rules are creating a price premium for low-emission iron, and plant operators are improving productivity and adding carbon capture to existing plants. The market is being shaped by new needs such as hydrogen-ready plants, hot charging of DRI into furnaces and verified low-carbon steel, which call for DRI with consistent quality and a documented carbon footprint. To realize the full techno-commercial potential of direct reduced iron, close collaboration between iron ore and pellet suppliers, technology providers, steelmakers, energy and hydrogen producers and policy makers will be essential.
Direct Reduced Iron (DRI) Market Overview:
Direct reduced iron, also called sponge iron, is iron made by removing oxygen from iron ore in solid form, without melting it. The ore is reduced using gas made from natural gas or from coal, and the product is used mainly as a clean iron source in electric arc furnaces, where it dilutes the residual elements found in scrap. DRI can be charged hot into a furnace, cooled and shipped, or briquetted into hot briquetted iron for transport. It is sold in pellet and lump forms and in grades defined by metallic iron (FeM) content, and it is produced by gas-based and coal-based processes.
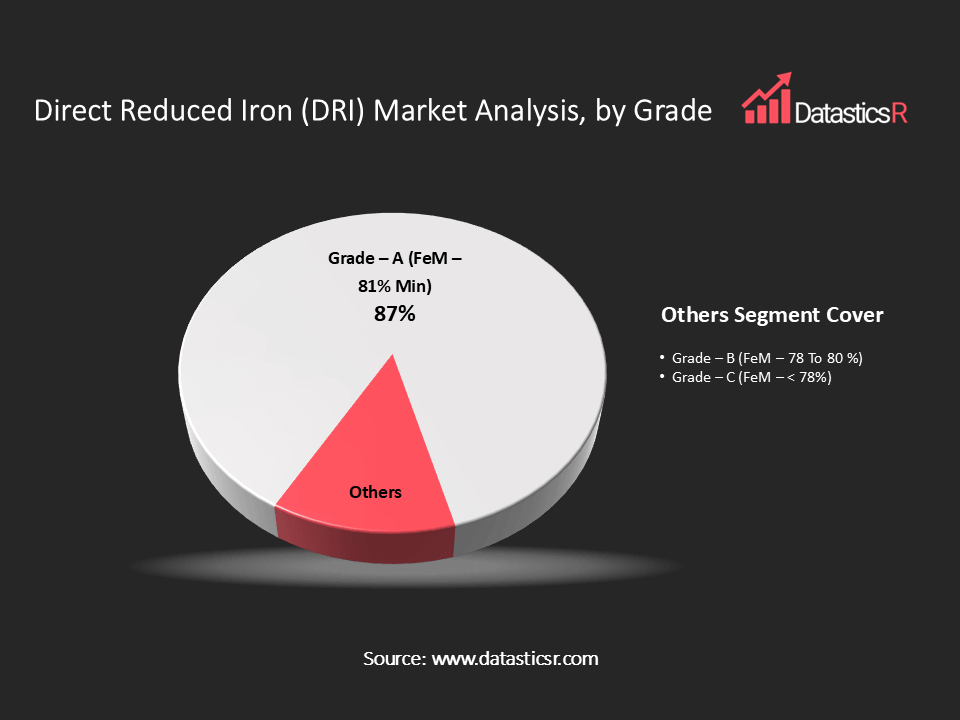
By grade, Grade – A (FeM – 81% Min) leads with an 87.4% share, followed by Grade – B (FeM – 78 To 80 %) and Grade – C (FeM – < 78%). By form, lumps lead the market. By production process, gas-based leads with more than half of the market share. By region, Asia Pacific leads with a 48.8% share, followed by Europe with 31.1% and North America with 13.1%. Latin America holds 4.3% and Middle East & Africa holds 2.7%.
The main trend in this market is the shift toward lower-carbon DRI, through hydrogen-ready plants, carbon capture and higher productivity at gas-based plants. This is supported by carbon border rules, by steel capacity expansion in Asia and by growth in electric arc furnace steelmaking.
| Drivers | Carbon Border Rules and Low-Emission Iron Projects to Drive Market Growth |
| Steel Capacity Expansion and Record DRI Plant Performance Across Geographies |
Carbon Border Rules and Low-Emission Iron Projects to Drive Market Growth
Steelmakers are building lower-carbon iron supply because carbon costs are now being applied to steel trade. The EU Carbon Border Adjustment Mechanism entered its definitive phase on 1 January 2026, applying carbon costs to imports of products such as steel. Several European projects are built around DRI: Stegra’s 2.1 million ton hydrogen-based DRI plant, which targets production in 2026, and planned DRI-based plants by ThyssenKrupp and Salzgitter in Germany, Tata Steel in the Netherlands and Hydnum Steel in Spain. Progress is uneven, however. ArcelorMittal postponed the final investment decision on its 2.3 million ton per annum hydrogen-based DRI plant in Gijón, Spain, citing the cost and slow development of green hydrogen, shortcomings in CBAM and the absence of a clear Spanish framework for green hydrogen, while continuing construction of an electric arc furnace at the site.
In North America, the focus is on cutting emissions from existing gas-based DRI. In September 2026, ExxonMobil started carbon capture and storage at Nucor’s DRI plant in Convent, Louisiana, with up to 800,000 tons of CO2 per year captured, transported and stored, supporting what the companies describe as the lowest-carbon DRI at scale in North America. In Asia and the Middle East, producers such as Jindal Steel in Oman already feed DRI hot into adjacent steelmaking, with Midrex reporting that 98% of the output of its Sohar plant is consumed as hot DRI, which saves reheating energy.
Since carbon pricing, customer demand and capital support are being applied in more than one region at the same time, they are expected to raise demand for high-grade and low-emission DRI, even as individual projects are delayed or rescheduled.
Steel Capacity Expansion and Record DRI Plant Performance Across Geographies
Growth in steel capacity in Asia and the Middle East is the main source of volume. Global DRI production reached 111.6 million tons in 2025, up 7.41% from 103.9 million tons in 2024, according to our analysis. In India, the Ministry of Steel reaffirmed in April 2026 its target of 300 million tons of crude steel capacity by 2030, compared with 168 million tons currently. AM/NS India began a Rs 60,000 crore expansion at its Hazira plant to raise capacity to 15 million tons, with commissioning expected by 2026.
Existing DRI plants are also being run harder. Midrex reported that Tosyali Algeria’s DRI II module, which started in August 2024, now holds the highest annual and monthly production and productivity of all Midrex plants. The Jindal Steel plant in Sohar, Oman set a new annual productivity record, and Qatar Steel’s two modules ran above their rated capacity. At least eight Midrex modules set annual production records in 2025, and ten operated for more than 8,000 hours.
This expansion and productivity gain is spread across several regions and fuels. It supports steady demand for DRI-grade iron ore pellets and lumps, natural gas and coal-based reductants, and shows that existing plants can supply more iron without new construction.
Direct Reduced Iron (DRI) Regional Market Outlook:
Asia Pacific is the largest market, with a 48.8% share. Demand is supported by India’s target of 300 million tons of steel capacity by 2030, large expansions such as AM/NS India’s Hazira plant, and a large base of gas-based and coal-based DRI producers.
Europe holds a 31.1% share. Demand is supported by the EU Carbon Border Adjustment Mechanism, hydrogen-based DRI projects by Stegra, ThyssenKrupp, Salzgitter and Tata Steel Netherlands, and the shift of integrated mills toward electric arc furnaces.
North America holds a 13.1% share. Demand is supported by Nucor’s gas-based DRI plant in Louisiana with its new carbon capture system, and by ArcelorMittal’s hot briquetted iron plant in Texas, which set a world monthly HBI record in September 2025.
Latin America holds a 4.3% share and Middle East & Africa holds a 2.7% share. Latin America includes Nucor’s Nu-Iron plant in Trinidad and Tobago, which achieved the highest DRI metallization of all Midrex plants in 2025, and the Middle East and North Africa include plants in Qatar, Oman, Saudi Arabia and Algeria that set production or productivity records.

Key Companies in Direct Reduced Iron (DRI) Market:
The market includes integrated steel producers, specialist DRI producers and technology suppliers. Midrex Technologies Inc (United States), a subsidiary of Kobe Steel Ltd (Japan), supplies the MIDREX gas-based direct reduction process, which has produced more than 1.5 billion tons of DRI since inception. ArcelorMittal and NUCOR operate DRI and hot briquetted iron plants in several countries, including Nucor’s Louisiana and Trinidad and Tobago plants. Tosyali Algeria A.S. and Qatar Steel operate Midrex-based plants that ran at or above rated capacity in 2025. AM/NS India, a joint venture of ArcelorMittal and Nippon Steel, is expanding its Hazira plant. JSW Ispat Special Products Limited, Gallantt Group of Industries and Welspun Group are steel producers in India, and Khouzestan Steel Company is a steel producer in Iran. Jindal Shadeed Iron & Steel LLC and Tuwairqi Steel Mills Limited are also included among the key players.
Key players include Qatar Steel, JSW Ispat Special Products Limited, Kobe Steel Ltd, ArcelorMittal, NUCOR, Midrex Technologies Inc, Khouzestan Steel Company, Gallantt Group of Industries, Welspun Group, Jindal Shadeed Iron & Steel LLC, AM/NS India, Tosyali Algeria A.S., Tuwairqi Steel Mills Limited and Others.
Key players include Qatar Steel, JSW Ispat Special Products Limited, Kobe Steel Ltd, ArcelorMittal, NUCOR, Midrex Technologies Inc, Khouzestan Steel Company, Gallantt Group of Industries, Welspun Group, Jindal Shadeed Iron & Steel LLC, AM/NS India, Tosyali Algeria A.S., Tuwairqi Steel Mills Limited and Others.
Key Developments in Direct Reduced Iron (DRI) Market:
| 1. ExxonMobil Starts Carbon Capture at Nucor’s DRI Plant in Louisiana: In September 2026, ExxonMobil began carbon capture and storage for Nucor’s DRI plant in Convent, Louisiana, with up to 800,000 tonnes of CO2 per year to be captured, transported and stored. |
| 2. Midrex Reports Record 82.17 Million Tonnes of Global DRI Production in 2025: Midrex reported that global DRI production rose 7.78% from 76.24 million tonnes in 2024, with at least eight modules setting annual records and Tosyali Algeria’s DRI II module holding the highest production and productivity of all Midrex plants. |
Direct Reduced Iron (DRI) Market Attributes:
| Market Value, 2025 | $US 31.3 Billion |
| Forecasted Market Value, 2036 | $US 70 Billion |
| CAGR (2026-2036) | 7.6% |
| Analysis Period | 2021-2036 |
| Historic Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Volume Unit | Tons |
| Value Unit | $US Billion |
| Market Segmentation | By Grade
By Form
By Production Process
By Region
|
| Companies Profiles |
|
| Customization Request | Available upon request |
1. Introduction
1.1. Report Scope
1.2. Market Segmentations and Definitions
1.3. Geographical Coverage
2. Executive Summary
2.1. Key Facts and Figures
2.2. Trends Impacting the Market
2.3. DatasticsR Growth Opportunity Matrix
3. Market Overview
3.1. Global Direct Reduced Iron (DRI) Market Analysis and Forecast, 2021-2036
3.1.1. Global Direct Reduced Iron (DRI) Market Size (Tons)
3.1.2. Global Direct Reduced Iron (DRI) Market Size ($US Bn)
3.2. Key Market Trends
3.3. Technology Roadmap and Developments
3.4. Market Dynamics
3.4.1. Drivers
3.4.2. Restraints
3.4.3. Opportunities
3.5. Porter’s Five Forces Analysis
3.6. PESTL Analysis
3.7. Industry SWOT Analysis
3.8. Regulatory Landscape
3.9. Value Chain Analysis
3.9.1. List of Raw Materials Suppliers
3.9.2. List of Manufacturers
3.9.3. List of Dealers / Distributors
3.9.4. List of Potential Customers
3.10. Impact of Current Geopolitical Scenario on the Market
4. Technical Analysis
4.1. Product Specifications Analysis
4.2. Technology Adoption and Emerging Technologies
4.3. R&D Trends and Patents Landscape
4.4. Cost Structure and Profitability Analysis
5. Global Production Output Analysis (Tons), by Region, 2025
5.1. North America
5.2. Europe
5.3. Asia Pacific
5.4. Latin America
5.5. Middle East and Africa
6. Import-export Analysis Volume (Tons) and Value ($US Bn), by Key Country, 2021-2025
7. Price Trend Analysis and Forecasting ($US/Ton), 2021-2036
7.1. Price Trend Analysis and Forecasting, by Grade
7.2. Price Trend Analysis and Forecasting, by Form
7.3. Price Trend Analysis and Forecasting, by Region
8. Global Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
9. Global Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
10. Global Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
11. Global Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Region, 2021-2036
12. North America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
13. North America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
14. North America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
15. U.S. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
16. U.S. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
17. U.S. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
18. Canada Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
19. Canada Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
20. Canada Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
21. Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
22. Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
23. Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
24. Germany Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
25. Germany Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
26. Germany Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
27. U.K. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
28. U.K. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
29. U.K. Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
30. France Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
31. France Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
32. France Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
33. Italy Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
34. Italy Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
35. Italy Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
36. Spain Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
37. Spain Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
38. Spain Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
39. Russia & CIS Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
40. Russia & CIS Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
41. Russia & CIS Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
42. Rest of Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
43. Rest of Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
44. Rest of Europe Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
45. Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
46. Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
47. Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
48. China Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
49. China Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
50. China Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
51. India Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
52. India Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
53. India Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
54. Japan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
55. Japan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
56. Japan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
57. South Korea Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
58. South Korea Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
59. South Korea Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
60. Taiwan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
61. Taiwan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
62. Taiwan Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
63. Australia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
64. Australia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
65. Australia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
66. ASEAN Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
67. ASEAN Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
68. ASEAN Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
69. Rest of Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
70. Rest of Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
71. Rest of Asia Pacific Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
72. Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
73. Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
74. Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
75. Brazil Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
76. Brazil Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
77. Brazil Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
78. Mexico Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
79. Mexico Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
80. Mexico Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
81. Argentina Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
82. Argentina Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
83. Argentina Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
84. Rest of Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
85. Rest of Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
86. Rest of Latin America Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
87. Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
88. Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
89. Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
90. Saudi Arabia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
91. Saudi Arabia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
92. Saudi Arabia Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
93. UAE Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
94. UAE Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
95. UAE Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
96. South Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
97. South Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
98. South Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
99. Rest of Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Grade, 2021-2036
100. Rest of Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Form, 2021-2036
101. Rest of Middle East & Africa Direct Reduced Iron (DRI) Market Analysis and Forecasting (Tons) ($US Bn), by Production Process, 2021-2036
102. Competition Landscape
102.1. Market Share Analysis (%), by Company, 2025
102.2. Competitive Benchmarking
102.3. Company Profiles
102.3.1. Qatar Steel
102.3.1.1. Company Overview
102.3.1.2. Business Portfolio
102.3.1.3. Financials
102.3.1.4. Geographical Footprint
102.3.1.5. SWOT Analysis
102.3.1.6. Recent Developments and Strategies
102.3.2. JSW Ispat Special Products Limited
102.3.2.1. Company Overview
102.3.2.2. Business Portfolio
102.3.2.3. Financials
102.3.2.4. Geographical Footprint
102.3.2.5. SWOT Analysis
102.3.2.6. Recent Developments and Strategies
102.3.3. Kobe Steel Ltd
102.3.3.1. Company Overview
102.3.3.2. Business Portfolio
102.3.3.3. Financials
102.3.3.4. Geographical Footprint
102.3.3.5. SWOT Analysis
102.3.3.6. Recent Developments and Strategies
102.3.4. ArcelorMittal
102.3.4.1. Company Overview
102.3.4.2. Business Portfolio
102.3.4.3. Financials
102.3.4.4. Geographical Footprint
102.3.4.5. SWOT Analysis
102.3.4.6. Recent Developments and Strategies
102.3.5. NUCOR
102.3.5.1. Company Overview
102.3.5.2. Business Portfolio
102.3.5.3. Financials
102.3.5.4. Geographical Footprint
102.3.5.5. SWOT Analysis
102.3.5.6. Recent Developments and Strategies
102.3.6. Midrex Technologies Inc
102.3.6.1. Company Overview
102.3.6.2. Business Portfolio
102.3.6.3. Financials
102.3.6.4. Geographical Footprint
102.3.6.5. SWOT Analysis
102.3.6.6. Recent Developments and Strategies
102.3.7. Khouzestan Steel Company
102.3.7.1. Company Overview
102.3.7.2. Business Portfolio
102.3.7.3. Financials
102.3.7.4. Geographical Footprint
102.3.7.5. SWOT Analysis
102.3.7.6. Recent Developments and Strategies
102.3.8. Gallantt Group of Industries
102.3.8.1. Company Overview
102.3.8.2. Business Portfolio
102.3.8.3. Financials
102.3.8.4. Geographical Footprint
102.3.8.5. SWOT Analysis
102.3.8.6. Recent Developments and Strategies
102.3.9. Welspun Group
102.3.9.1. Company Overview
102.3.9.2. Business Portfolio
102.3.9.3. Financials
102.3.9.4. Geographical Footprint
102.3.9.5. SWOT Analysis
102.3.9.6. Recent Developments and Strategies
102.3.10. Jindal Shadeed Iron & Steel LLC
102.3.10.1. Company Overview
102.3.10.2. Business Portfolio
102.3.10.3. Financials
102.3.10.4. Geographical Footprint
102.3.10.5. SWOT Analysis
102.3.10.6. Recent Developments and Strategies
102.3.11. AM/NS India
102.3.11.1. Company Overview
102.3.11.2. Business Portfolio
102.3.11.3. Financials
102.3.11.4. Geographical Footprint
102.3.11.5. SWOT Analysis
102.3.11.6. Recent Developments and Strategies
102.3.12. Tosyali Algeria A.S.
102.3.12.1. Company Overview
102.3.12.2. Business Portfolio
102.3.12.3. Financials
102.3.12.4. Geographical Footprint
102.3.12.5. SWOT Analysis
102.3.12.6. Recent Developments and Strategies
102.3.13. Tuwairqi Steel Mills Limited
102.3.13.1. Company Overview
102.3.13.2. Business Portfolio
102.3.13.3. Financials
102.3.13.4. Geographical Footprint
102.3.13.5. SWOT Analysis
102.3.14. Recent Developments and Strategies
102.3.15. Others
103. Appendix
- Get Started -
Get insights that lead to new growth opportunities
- Talk to Experts -
Get answers to your queries on this report from our experts
Frequently Asked Questions
The global Direct Reduced Iron (DRI) market in 2025 was $US 31.3 Billion.
The global Direct Reduced Iron (DRI) market will be $US 70 Billion by 2036.
The expected growth rate (CAGR%) of the global Direct Reduced Iron (DRI) market is 7.6% for the period 2026-2036.
Carbon Border Rules and Low-Emission Iron Projects to Drive Market Growth, and Steel Capacity Expansion and Record DRI Plant Performance Across Geographies.
Grade – A (FeM – 81% Min) was the largest segment in grade segment with around 87.4% revenue share among all in Direct Reduced Iron (DRI) Market in 2025.
Asia Pacific was the leading regions for Direct Reduced Iron (DRI) holding 87.4% of the global market in 2025.
Qatar Steel, JSW Ispat Special Products Limited, Kobe Steel Ltd, ArcelorMittal, NUCOR, Midrex Technologies Inc, Khouzestan Steel Company, Gallantt Group of Industries, Welspun Group, Jindal Shadeed Iron & Steel LLC, AM/NS India, Tosyali Algeria A.S., Tuwairqi Steel Mills Limited and Others.