Robots in Defense Manufacturing Market
Robots in Defense Manufacturing Market (Robot Type: Articulated Robots, Collaborative Robots (Cobots), Cartesian Robots, SCARA Robots, Delta Robots and Additive Manufacturing Robots; Application: Military Aircraft & Helicopters, Naval Shipbuilding, Armored Vehicles, Missiles & Munitions and Defense Electronics; and Manufacturing Facility: Part Manufacturing, Sub-System & Sub-Assembly Manufacturing, Final Assembly Plants, Ammunition Manufacturing Plants, Defense Electronics Manufacturing Plants and MRO Facilities) – Global Industry Analysis, Shares, Growth, Trends and Forecast 2021-2036
| Format: PDF/PPT/Excel
| Product ID:
4836
| Report Version:
August 2026
- Report Preview
- Table of Content
- Request Customization
Market Snappshot
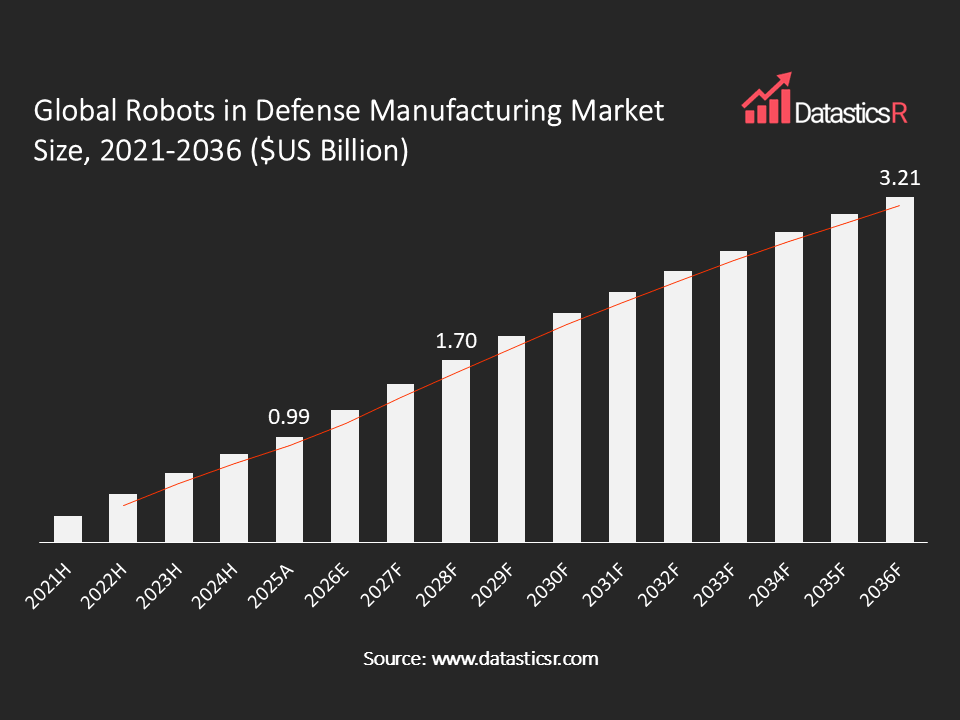
- Market Size in 2025: $US 0.99 Bn
- Forecast Market by 2036: $US 3.21 Bn
- CAGR for the Period 2026-2036: 10%
- Top Region in Terms of Market Share: North America (34%)
- Key Players: KUKA Robotics, ABB Robotics, FANUC Corporation, Bosch Rexroth, Yamaha Robotics, EPSON Robots, Mitsubishi Electric, Universal Robots, Path Robotics, GrayMatter Robotics, Stäubli Robotics and Others
Analyst Viewpoint:
Robotics on the defense shop floor has quietly shifted from a cost-saving option to a capacity necessity. Shipbuilders, munitions plants, and aerostructure manufacturers are being asked to deliver at wartime-adjacent volumes while the skilled welders, machinists, and assemblers they need simply are not available in sufficient numbers, and that gap is what is really funding the robot order books rather than automation for its own sake. The technology story worth watching is the move from single-purpose arms to physical-AI systems that can handle the variable, non-repetitive work defense hardware demands, welding a submarine hull section is nothing like welding a car door. Articulated robots still dominate installed volume because they underpin the heaviest structural work, but additive manufacturing robots are the fastest-growing category by a wide margin, prized for their ability to reproduce obsolete parts for legacy platforms where the original tooling and suppliers no longer exist. What will separate durable winners from one-off pilots is whether a robotics supplier can move from a single welding cell to a full production line integration, tied to a shipbuilder’s or prime’s long-term capacity plan rather than a single grant-funded demonstration. Performance-based, multi-year agreements of the kind now appearing in naval shipbuilding are the clearest signal that this market is graduating from proof-of-concept to production infrastructure.
Robots in Defense Manufacturing Market Overview:
Robots used in defense manufacturing, inside a defense manufacturing plant, are treated within defense industry terminology as industrial robots, deployed across part manufacturing, sub-system and sub-assembly manufacturing, final assembly plants, ammunition manufacturing plants, defense electronics manufacturing plants, and maintenance, repair and overhaul (MRO) facilities. They span six robot types, articulated robots, collaborative robots (cobots), Cartesian robots, SCARA robots, delta robots, and additive manufacturing robots, each suited to a different combination of precision, payload, and repeatability requirements across defense production.
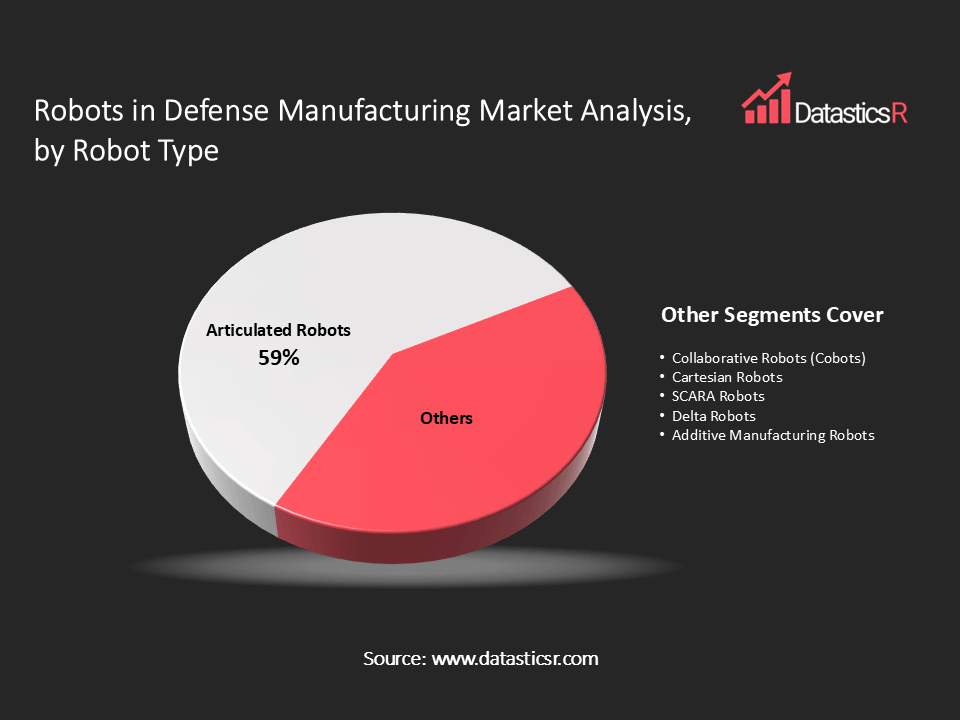
By robot type, articulated robots lead with an estimated 59% revenue share in 2025, reflecting their central role in heavy-duty titanium welding, structural drilling, armored vehicle framework assembly, and large-component handling, while additive manufacturing robots are the fastest-growing category, expanding on demand for 3D-printed drone components and the reproduction of obsolete parts for legacy platforms whose original equipment manufacturers no longer exist. By application, military aircraft & helicopters represent the largest segment at an estimated 42% share, given the sheer number of precision drilling, welding, and inspection operations involved in airframe manufacturing, while missiles & munitions is the fastest-growing application, driven by replenishment-scale production demands. By manufacturing facility, part manufacturing operations rank first in robot adoption, followed by sub-system and sub-assembly manufacturing and final assembly plants, with ammunition manufacturing plants, defense electronics manufacturing plants, and MRO facilities rounding out the ranking.
The shift toward physical AI, robots capable of handling variable, non-repetitive tasks rather than fixed, pre-programmed motions, is the defining trend reshaping this market, as shipbuilders and aerostructure manufacturers look to automate welding, sanding, and inspection work that has historically resisted automation because of its irregularity.
By robot type, articulated robots lead with an estimated 59% revenue share in 2025, reflecting their central role in heavy-duty titanium welding, structural drilling, armored vehicle framework assembly, and large-component handling, while additive manufacturing robots are the fastest-growing category, expanding on demand for 3D-printed drone components and the reproduction of obsolete parts for legacy platforms whose original equipment manufacturers no longer exist. By application, military aircraft & helicopters represent the largest segment at an estimated 42% share, given the sheer number of precision drilling, welding, and inspection operations involved in airframe manufacturing, while missiles & munitions is the fastest-growing application, driven by replenishment-scale production demands. By manufacturing facility, part manufacturing operations rank first in robot adoption, followed by sub-system and sub-assembly manufacturing and final assembly plants, with ammunition manufacturing plants, defense electronics manufacturing plants, and MRO facilities rounding out the ranking.
The shift toward physical AI, robots capable of handling variable, non-repetitive tasks rather than fixed, pre-programmed motions, is the defining trend reshaping this market, as shipbuilders and aerostructure manufacturers look to automate welding, sanding, and inspection work that has historically resisted automation because of its irregularity.
| Drivers | Rising Global Defense Budgets and Manufacturing Capacity Expansion |
| Persistent Skilled-Labor Shortages Driving Physical AI and Robotics Adoption on the Shop Floor |
Rising Global Defense Budgets and Manufacturing Capacity Expansion
Global defense spending reached approximately $2.63 trillion in 2025, up from $2.48 trillion in 2024, with the sharpest increases concentrated in Europe and the Middle East. NATO allies have committed to lifting overall security-related spending to 5% of GDP by 2035, with 3.5% earmarked for direct defense expenditure, and in 2025 alone European allies and Canada raised defense spending by 20% year-on-year. That spending is increasingly directed not just at equipment purchases but at expanding the underlying industrial base able to build the equipment in the first place.
Naval shipbuilding illustrates the pattern most clearly. The U.S. Navy’s fiscal year 2027 shipbuilding plan calls for 75 new battle force ships, 47 support boats, and 47 medium unmanned surface vessels over five years, a volume the existing skilled workforce cannot support without automation. In Europe, the rapid build-out of defense manufacturing capacity is drawing specialist industrial robotics suppliers directly into the sector, including dedicated defense-automation partnerships and symposia aimed at scaling production systems for next-generation military manufacturing.
This capacity expansion spans nearly every category tracked in this market, aircraft and helicopter structures, naval vessels, armored vehicle hulls, missile and munitions casings, and defense electronics assemblies, all of which require the same underlying mix of welding, drilling, precision placement, and inspection that industrial robots are built to perform at scale.
Naval shipbuilding illustrates the pattern most clearly. The U.S. Navy’s fiscal year 2027 shipbuilding plan calls for 75 new battle force ships, 47 support boats, and 47 medium unmanned surface vessels over five years, a volume the existing skilled workforce cannot support without automation. In Europe, the rapid build-out of defense manufacturing capacity is drawing specialist industrial robotics suppliers directly into the sector, including dedicated defense-automation partnerships and symposia aimed at scaling production systems for next-generation military manufacturing.
This capacity expansion spans nearly every category tracked in this market, aircraft and helicopter structures, naval vessels, armored vehicle hulls, missile and munitions casings, and defense electronics assemblies, all of which require the same underlying mix of welding, drilling, precision placement, and inspection that industrial robots are built to perform at scale.
Persistent Skilled-Labor Shortages Driving Physical AI and Robotics Adoption on the Shop Floor
The second driver is structural rather than budgetary: defense manufacturers simply cannot hire enough welders, machinists, and assemblers to meet the volumes now being demanded of them. HII, the largest U.S. military shipbuilder, signed long-term, performance-based production agreements worth up to $900 million with Path Robotics and GrayMatter Robotics in August 2026 specifically to bring physical-AI welding and finishing robots into aircraft carrier, submarine, destroyer, and unmanned surface vessel production, after publicly citing chronic welder shortages as a national security risk to shipbuilding capacity.
HII expects to outsource more than 2.5 million hours of shipbuilding work in 2026 alone, a 30% increase over 2025, and is simultaneously expanding a distributed manufacturing network so more structural sections can be fabricated outside its primary yards. Robotics suppliers are positioning their systems, such as intelligent welding cells capable of handling the variable, non-repetitive welds that traditional fixed automation cannot, as the mechanism that lets a fixed workforce keep pace with rising build volumes.
This dynamic is not confined to shipbuilding. Aerospace, armored vehicle, and munitions manufacturers face the same shortage of specialized labor, and the same physical-AI robotics suppliers, and defense-focused system integrators are increasingly marketing directly into these adjacent categories, reinforcing collaborative robots and additive manufacturing robots as the fastest-growing categories within this market.
HII expects to outsource more than 2.5 million hours of shipbuilding work in 2026 alone, a 30% increase over 2025, and is simultaneously expanding a distributed manufacturing network so more structural sections can be fabricated outside its primary yards. Robotics suppliers are positioning their systems, such as intelligent welding cells capable of handling the variable, non-repetitive welds that traditional fixed automation cannot, as the mechanism that lets a fixed workforce keep pace with rising build volumes.
This dynamic is not confined to shipbuilding. Aerospace, armored vehicle, and munitions manufacturers face the same shortage of specialized labor, and the same physical-AI robotics suppliers, and defense-focused system integrators are increasingly marketing directly into these adjacent categories, reinforcing collaborative robots and additive manufacturing robots as the fastest-growing categories within this market.
Robots in Defense Manufacturing Regional Market Outlook:
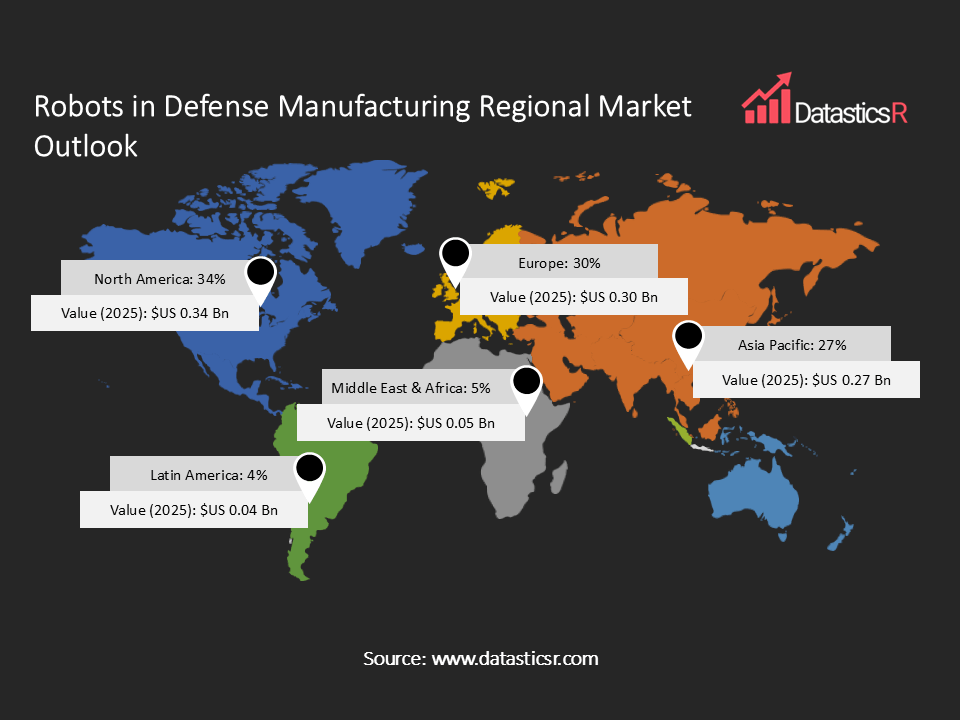
North America is the largest market for robots in defense manufacturing, with an estimated 34% market share, underpinned by record U.S. defense budgets, a first-ever trillion-dollar defense budget request, and large-scale shipbuilding and aerospace automation programs such as HII’s High-Yield Production Robotics initiative.
Europe holds an estimated 30% market share, fueled by NATO’s defense-investment pledge, rapid expansion of European defense manufacturing capacity following the Russia-Ukraine conflict, and growing collaboration between industrial robotics specialists and national defense-industry associations.
Asia Pacific accounts for an estimated 27% share and is the fastest-growing region, driven by rising defense budgets across China, India, Japan, South Korea, and other regional players investing heavily in domestic defense manufacturing and automation capacity.
Middle East & Africa represents an estimated 5% market share, backed by Gulf state investment in domestic defense-industrial capability, while Latin America represents an estimated 4% share, reflecting a smaller but steadily growing defense-industrial base.
Europe holds an estimated 30% market share, fueled by NATO’s defense-investment pledge, rapid expansion of European defense manufacturing capacity following the Russia-Ukraine conflict, and growing collaboration between industrial robotics specialists and national defense-industry associations.
Asia Pacific accounts for an estimated 27% share and is the fastest-growing region, driven by rising defense budgets across China, India, Japan, South Korea, and other regional players investing heavily in domestic defense manufacturing and automation capacity.
Middle East & Africa represents an estimated 5% market share, backed by Gulf state investment in domestic defense-industrial capability, while Latin America represents an estimated 4% share, reflecting a smaller but steadily growing defense-industrial base.
Key Companies in Robots in Defense Manufacturing Market:
The competitive field spans established industrial robotics manufacturers with deep multi-axis and precision-motion engineering heritage, and a newer wave of defense-focused physical-AI robotics specialists. KUKA Robotics, ABB Robotics, FANUC, Bosch Rexroth, Yamaha Robotics, EPSON, Mitsubishi Electric, and Universal Robots supply the core articulated, Cartesian, SCARA, delta, and collaborative robot platforms deployed across defense manufacturing facilities today, while specialists such as Path Robotics, GrayMatter Robotics, and Stäubli Robotics compete on physical-AI welding, variable-task automation, and dedicated defense-manufacturing production partnerships. Recent activity has centered on multi-year, performance-based production agreements with shipbuilders and primes, expansion of defense-specific automation partnerships in Europe, and growing use of additive manufacturing robots to solve legacy-parts obsolescence.
Key Developments in Robots in Defense Manufacturing Market:
| 1. HII Signs Performance-Based Production Agreements with Path Robotics and GrayMatter Robotics: In August 2026, HII announced long-term, performance-based production agreements worth up to $900 million with Path Robotics and GrayMatter Robotics to bring physical-AI welding and finishing robotics into U.S. Navy shipbuilding programs spanning aircraft carriers, submarines, destroyers, amphibious ships, future frigates, and unmanned surface vessels. |
| 2. Stäubli Robotics Expands into European Defense Manufacturing Automation: In May 2026, Stäubli Robotics announced an expanded partnership strategy and a dedicated defense-automation symposium in Germany aimed at building highly automated, flexible production systems for Europe’s rapidly expanding defense manufacturing sector. |
Robots in Defense Manufacturing Market Attributes:
| Market Value, 2025 | $US 0.99 Billion |
| Forecasted Market Value, 2036 | $US 3.21 Billion |
| CAGR (2026-2036) | 10.0% |
| Analysis Period | 2021-2036 |
| Historic Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Volume Unit | Units |
| Value Unit | $US Million |
| Market Segmentation | By Robot Type
By Application
By Manufacturing Facility
By Region
|
| Companies Profiles |
|
| Customization Request | Available upon request |
1. Introduction
1.1. Report Scope
1.2. Market Segmentations and Definitions
1.3. Geographical Coverage
2. Executive Summary
2.1. Key Facts and Figures
2.2. Trends Impacting the Market
2.3. DatasticsR Growth Opportunity Matrix
3. Market Overview
3.1. Global Robots in Defense Manufacturing Market Analysis and Forecast, 2021-2036
3.1.1. Global Robots in Defense Manufacturing Market Size (Units)
3.1.2. Global Robots in Defense Manufacturing Market Size ($US Bn)
3.2. Key Market Trends
3.3. Technology Roadmap and Developments
3.4. Market Dynamics
3.4.1. Drivers
3.4.2. Restraints
3.4.3. Opportunities
3.5. Porter’s Five Forces Analysis
3.6. PESTL Analysis
3.7. Industry SWOT Analysis
3.8. Regulatory Landscape
3.9. Value Chain Analysis
3.9.1. List of Component Suppliers
3.9.2. List of Software Providers
3.9.3. List of Robots Manufacturers
3.9.4. List of System Integrators
3.9.5. List of Potential Customers
3.10. Impact of Current Geopolitical Scenario on the Market
4. Technical Analysis
4.1. Defense Manufacturing Specific Use-Cases
4.2. Technical Specifications Analysis
4.3. Details of System Integration Process
4.4. Technology Adoption and Emerging Technologies
4.5. R&D Trends and Patents Landscape
4.6. Cost Structure and Profitability Analysis
5. Global Installation Analysis (Units), by Region, 2025
5.1. North America
5.2. Europe
5.3. Asia Pacific
5.4. Latin America
5.5. Middle East and Africa
6. Import-export Analysis Volume (Units) and Value ($US Bn), by Key Country, 2021-2025
7. Price Trend Analysis and Forecasting ($US/Unit), 2021-2036
7.1. Price Trend Analysis and Forecasting, by Robot Type
7.2. Price Trend Analysis and Forecasting, by Region
8. Global Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
9. Global Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
10. Global Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
11. Global Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Region, 2021-2036
12. North America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
13. North America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
14. North America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
15. U.S. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
16. U.S. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
17. U.S. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
18. Canada Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
19. Canada Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
20. Canada Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
21. Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
22. Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
23. Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
24. Germany Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
25. Germany Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
26. Germany Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
27. U.K. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
28. U.K. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
29. U.K. Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
30. France Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
31. France Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
32. France Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
33. Italy Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
34. Italy Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
35. Italy Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
36. Spain Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
37. Spain Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
38. Spain Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
39. Russia & CIS Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
40. Russia & CIS Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
41. Russia & CIS Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
42. Rest of Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
43. Rest of Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
44. Rest of Europe Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
45. Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
46. Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
47. Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
48. China Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
49. China Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
50. China Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
51. India Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
52. India Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
53. India Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
54. Japan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
55. Japan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
56. Japan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
57. South Korea Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
58. South Korea Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
59. South Korea Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
60. Taiwan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
61. Taiwan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
62. Taiwan Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
63. Australia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
64. Australia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
65. Australia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
66. ASEAN Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
67. ASEAN Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
68. ASEAN Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
69. Rest of Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
70. Rest of Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
71. Rest of Asia Pacific Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
72. Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
73. Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
74. Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
75. Brazil Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
76. Brazil Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
77. Brazil Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
78. Mexico Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
79. Mexico Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
80. Mexico Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
81. Argentina Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
82. Argentina Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
83. Argentina Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
84. Rest of Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
85. Rest of Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
86. Rest of Latin America Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
87. Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
88. Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
89. Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
90. Saudi Arabia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
91. Saudi Arabia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
92. Saudi Arabia Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
93. UAE Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
94. UAE Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
95. UAE Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
96. South Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
97. South Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
98. South Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
99. Rest of Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), By Robot Type, 2021-2036
100. Rest of Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Application, 2021-2036
101. Rest of Middle East & Africa Robots in Defense Manufacturing Market Analysis and Forecasting (Units) ($US Bn), by Manufacturing Facility, 2021-2036
102. Competition Landscape
102.1. Market Share Analysis (%), by Company, 2025
102.2. Competitive Benchmarking
102.3. Company Profiles
102.3.1. KUKA Robotics
102.3.1.1. Company Overview
102.3.1.2. Business Portfolio
102.3.1.3. Financials
102.3.1.4. Geographical Footprint
102.3.1.5. SWOT Analysis
102.3.1.6. Recent Developments and Strategies
102.3.2. ABB Robotics
102.3.2.1. Company Overview
102.3.2.2. Business Portfolio
102.3.2.3. Financials
102.3.2.4. Geographical Footprint
102.3.2.5. SWOT Analysis
102.3.2.6. Recent Developments and Strategies
102.3.3. FANUC Corporation
102.3.3.1. Company Overview
102.3.3.2. Business Portfolio
102.3.3.3. Financials
102.3.3.4. Geographical Footprint
102.3.3.5. SWOT Analysis
102.3.3.6. Recent Developments and Strategies
102.3.4. Bosch Rexroth
102.3.4.1. Company Overview
102.3.4.2. Business Portfolio
102.3.4.3. Financials
102.3.4.4. Geographical Footprint
102.3.4.5. SWOT Analysis
102.3.4.6. Recent Developments and Strategies
102.3.5. Yamaha Robotics
102.3.5.1. Company Overview
102.3.5.2. Business Portfolio
102.3.5.3. Financials
102.3.5.4. Geographical Footprint
102.3.5.5. SWOT Analysis
102.3.5.6. Recent Developments and Strategies
102.3.6. EPSON Robots
102.3.6.1. Company Overview
102.3.6.2. Business Portfolio
102.3.6.3. Financials
102.3.6.4. Geographical Footprint
102.3.6.5. SWOT Analysis
102.3.6.6. Recent Developments and Strategies
102.3.7. Mitsubishi Electric
102.3.7.1. Company Overview
102.3.7.2. Business Portfolio
102.3.7.3. Financials
102.3.7.4. Geographical Footprint
102.3.7.5. SWOT Analysis
102.3.7.6. Recent Developments and Strategies
102.3.8. Universal Robots
102.3.8.1. Company Overview
102.3.8.2. Business Portfolio
102.3.8.3. Financials
102.3.8.4. Geographical Footprint
102.3.8.5. SWOT Analysis
102.3.8.6. Recent Developments and Strategies
102.3.9. Path Robotics
102.3.9.1. Company Overview
102.3.9.2. Business Portfolio
102.3.9.3. Financials
102.3.9.4. Geographical Footprint
102.3.9.5. SWOT Analysis
102.3.9.6. Recent Developments and Strategies
102.3.10. GrayMatter Robotics
102.3.10.1. Company Overview
102.3.10.2. Business Portfolio
102.3.10.3. Financials
102.3.10.4. Geographical Footprint
102.3.10.5. SWOT Analysis
102.3.10.6. Recent Developments and Strategies
102.3.11. Stäubli Robotics
102.3.11.1. Company Overview
102.3.11.2. Business Portfolio
102.3.11.3. Financials
102.3.11.4. Geographical Footprint
102.3.11.5. SWOT Analysis
102.3.11.6. Recent Developments and Strategies
102.3.12. Others
103. Appendix
- Get Started -
Get insights that lead to new growth opportunities
- Talk to Experts -
Get answers to your queries on this report from our experts
Frequently Asked Questions
The global Robots in Defense Manufacturing market in 2025 was $US 0.99 Billion.
The global Robots in Defense Manufacturing market will be $US 3.21 Billion by 2036.
The expected growth rate (CAGR%) of the global Robots in Defense Manufacturing market is 10% for the period 2026-2036.
Rising Global Defense Budgets and Manufacturing Capacity Expansion and Persistent Skilled-Labor Shortages Driving Physical AI and Robotics Adoption on the Shop Floor.
Articulated Robot was the largest segment in robot type with around 59% revenue share among all in Robots in Defense Manufacturing Market in 2025.
North America was the leading regions for Robots in Defense Manufacturing holding 34% of the global market in 2025.
KUKA Robotics, ABB Robotics, FANUC Corporation, Bosch Rexroth, Yamaha Robotics, EPSON Robots, Mitsubishi Electric, Universal Robots, Path Robotics, GrayMatter Robotics, Stäubli Robotics and Others.